

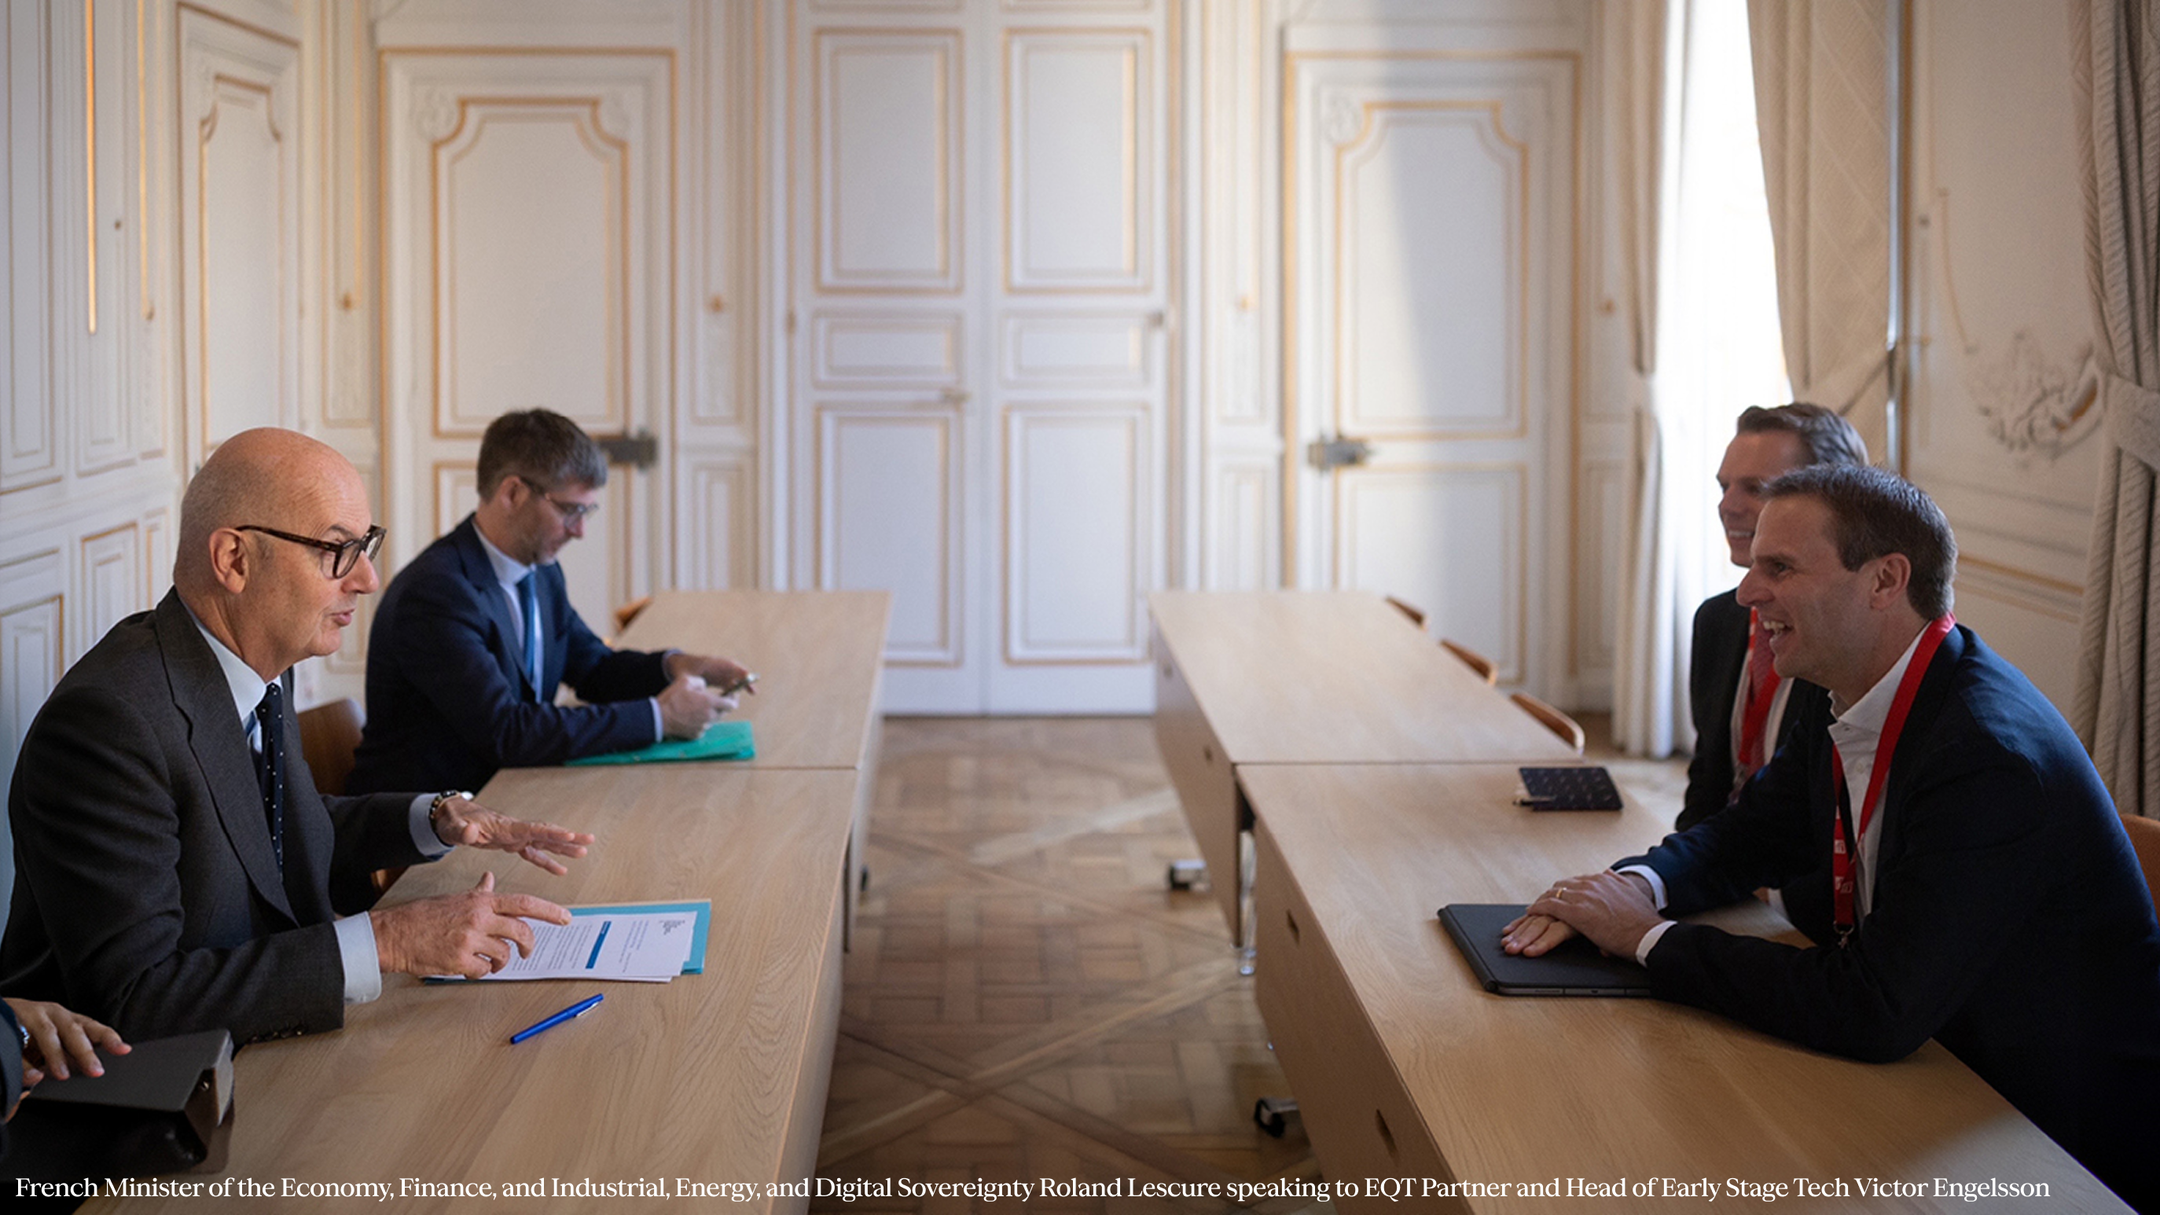
The Time For Talk About European Tech is Over, Now is Time For Action

Europe is finally realizing its ambition to successfully nurture a generation of world leading technology companies, argues EQT Partner and Head of Early Stage Tech Victor Englesson.
This article was adapted from a speech given by Victor Englesson at the Ambition Europe conference in Paris on October 5th, 2026.
In 1946, Marcus “Dodde” Wallenberg wrote down a sentence in a letter to his brother that his family had been living by for almost a century already: "To move from the old to what is about to come is the only tradition worth keeping."
Eighty years on, that sentence has become central to EQT's operating system and mindset - we call it “future proofing” companies.
In a world that is becoming increasingly short term, transactional and polarized those institutions that are optimizing for the long-term have a competitive advantage.
But a long-term vision is only worth something if you act on it, if you are actually able to move to what is about to come. Vision and action together is what matters.
Unlike the Wallenbergs, we at EQT do not own our companies for centuries as our investors expect their capital back.
EQT started in Stockholm in 1994 with a single fund. As of 2026, we manage more than €340bn across 26 offices around the world. But our roots are European, and when we took EQT public, we decided to list the firm in Stockholm, on a European stock exchange. Over the last five years, we have invested around €120bn in Europe and over the next five years, we will invest another €250bn.
When we invest in a company, we develop what we call a “full potential plan”. It centers around one question: if this company had unlimited resources, what could it then become? And then we work backwards from that vision to the actions we must take today to deliver it. It’s an expansive mindset that encourages risk taking in a controlled manner.
For thirty years, we have developed full potential plans for companies. But the most important full potential we now need to develop together is the full potential plan for Europe.
Imagining Europe in 2035
So let us dream a little and try to picture Europe in 2035, in a world where everything goes right.
Let’s first focus on growth. Over the last decade, Europe has transferred more than €1.2tn in value to mainly the U.S. by selling our tech companies too early. But in 2035, that flow has reversed. Europe has trillion-euro tech companies headquartered here, listed here, hiring here and winning globally from here.
Second, the flywheel and ecosystem: Scaled tech companies produce the next generation of founders, operators and angel investors. This is what built Silicon Valley. And the fundamentals of such an ecosystem already exist here. Look at the founders who came out of Spotify or the alumni networks already forming around Mistral. The flywheel is starting to gain real momentum and by 2035 it is operating at full speed.
Third, sovereignty. ASML already proves that European tech companies can build something the entire world depends on. In 2035, Europe will have many such companies, across AI, quantum, space, biotech, defence and advanced industrial systems. And with them, Europe is back to growth and at the same time secure its independence
This is of course hypothetical and none of it is guaranteed, but the good news is that we are already putting in place many of the measures needed to make it happen.
The Scaleup Europe Fund
Our continent does not lack ideas, talent or ambition. It lacks growth capital, deployed with speed, scale and conviction. Many of our promising startups too often need to look outside Europe for capital as they scale into world-leading champions. And when the capital comes from somewhere else, eventually the company goes there too.
The European Commission and a group of founding investors hopes to change this dynamic. The Scaleup Europe Fund, which targets more than €5bn to support Europe’s most promising technology companies from Series B through to pre-IPO, is the largest fund of its kind ever created in Europe. It aims to back breakthroughs when they matter most — a first factory, a new clinical program, the next generation of chips. It steps in, in the moments when substantial capital and risk taking is needed.
EQT was awarded this mandate in May. Since then, we have screened well over a thousand companies and met more than 250. We have announced seven investments in just a month and invested €1bn. These include the fund’s debut investment in Finland-based satellite imaging company ICEYE in August, and Sweden-based AI healthcare startup Tandem Health in September.
We believe that founders across Europe are choosing the Scaleup Europe Fund because they want European capital anchoring their rounds. We can also see that the fund’s capital attracts additional capital from other global investors, corporations and strategic partners into the companies and rounds we lead. Every euro the fund invests, it helps mobilise more.
Ecosystem catalyst
From the very beginning, EQT's identity has rested on three words: “more than capital”. And nowhere does that apply more than to the Scaleup Europe Fund. Our ambition is for the fund to be a catalyst for the whole ecosystem:
- Corporate partnerships and offtake agreements that give scaleups their first big customers.
- Talent networks that bring world-class operators to Europe.
- And deeper collaboration between the public and private sectors.
So why am I so confident Europe can reach its full potential? Because for the first time, all the right ingredients are on the table at once. We have
- Ambitious and talented founders who want to stay and build from Europe.
- We have a pipeline of tech scaleups growing stronger by the month.
- We have European capital mobilizing to support.
- And we have structural reforms high on the agenda.
Each of these alone is encouraging and together, they can be the game changer Europe has been waiting for.
But a moment can slip away if we don’t seize it. It requires action from all of us.
Policymakers can do a great deal: An ambitious EU-INC, and a savings and investment union that puts European capital to work. But the business community must act too; invest in Europe, partner with European firms, list on European exchanges.
The Wallenbergs never wrote a manifesto about long-term ownership. They simply practised it. That is the tradition worth keeping: not the talk but the action.
Statements contained in this Article that are not historical facts are based on current expectations, assumptions, opinions, and/or beliefs of the Author. Such statements are not facts and involve known and unknown risks, uncertainties, and other factors. Prospective Investors in the Scaleup Europe Fund should not rely on these statements as if they were fact. Moreover, certain information contained in this Article may constitute "forward-looking statements", which can be identified by the use of forward-looking terminology such as "may", "might”, “will”, “expect”, “target”, “intend” or "believe", or the negatives thereof or other variations thereon or comparable terminology. Any forward-looking statements in this Article are based upon current assumptions and views, may be simplified and may depend on events outside of the Author’s control. Other events that were not taken into account may occur and may significantly affect the analysis herein. Therefore, changes to any assumptions may have a material impact on any forward-looking statements. Actual results may therefore be materially different from any forward-looking statements in this Article.
The information contained herein does not constitute an offer to sell, nor a solicitation of an offer to buy, any security, and may not be used or relied upon in connection with any offer or solicitation. Any offer or solicitation in respect of any fund will be made only through a confidential private placement memorandum and related documents which will be furnished to qualified investors on a confidential basis in accordance with applicable laws and regulations. Any securities referred to herein have not been and will not be registered under the U.S. Securities Act of 1933, as amended (the “Securities Act”), and may not be offered or sold without registration thereunder or pursuant to an available exemption therefrom. Any offering of securities to be made in the United States would have to be made by means of an offering document that would be obtainable from the issuer or its agents and would contain detailed information about the issuer of the securities and its management, as well as financial information. The securities may not be offered or sold in the United States absent registration or an exemption from registration.

ThinQ by EQT: A publication where private markets meet open minds. Join the conversation – [email protected]
On the topic ofPrivate markets

Exclusive News and Insights Every Month
Sign up to subscribe to the EQT newsletter.