

Henry Steinberg: Why Nearshoring can be the Next Big Thing for Warehouse Demand in the US


Why Americans can, and should, expect more from the latest nearshoring trend in the U.S. real estate market.
Many are pointing to politics as the cause of industrial nearshoring in the U.S. right now, but if investors want to find the real origin they have to look back to the pandemic. I remember at the height of Covid-19, a major drug distributor asked us for a few short-term leases on several air-conditioned units in order to distribute the new vaccines. In normal times, we’d insist on long-term leases, but these weren’t normal times.
“Nearshoring is reshaping the warehouse real estate market. It’s not a short-term trend – this is a structural shift in how businesses manage their supply chains.”
We figured doing good is just good business and if we could help curb the number of cases while also ensuring our clients’ returns were protected, we figured it was a win-win situation. So we signed the deal.
Although we didn’t know it at the time, it set a precedent for what was to come.
The pandemic exposed vulnerabilities in global supply chains. Before 2020, “just-in-time” inventory was the gold standard. Companies minimized stock, kept operations lean, and maximized efficiency. But then supply chain disruptions hit. The system buckled. Companies found themselves with empty shelves and delayed products, all because their supply chains were stretched too thin.
In the immediate aftermath, the solution was simple: stockpile. Companies flooded their warehouses with inventory, ensuring they’d have enough supply to weather future storms. But the pendulum has swung back. Now, the conversation has shifted from “just-in-time” to a hybrid model where flexibility and resilience are key. This is where nearshoring comes in.
“Whether it’s a medical company distributing vaccines or a manufacturer producing chips, businesses want to be closer to their customers. And that means they need more warehouse space, more industrial land, and more power.”
While the first act in this drama was all about logistics and e-commerce, the second is focusing on manufacturing and specialist industries. Many businesses, especially in the U.S., are now reconsidering the location of their manufacturing facilities. For years, China was the go-to for low-cost, efficient production. But during the pandemic, companies saw the downside of having their production facilities so far away. If a port or border shuts down, everything ground to a halt. Now, they’re bringing manufacturing closer to home – to Mexico, or even the U.S.
According to U.S. Census Bureau data, Mexico overtook China as America’s largest trading partner in 2023. Why Mexico? It’s simple: increasingly skilled labor, proximity to the U.S., and favorable trade agreements. Mexico has always been a hub for automotive and light manufacturing, but now, it’s taking on more sophisticated production processes – consumer tech and even some advanced machinery. Companies are setting up shop in places like Tijuana, not just for assembly but for true manufacturing.
This shift is creating significant demand for industrial space. We’re seeing a multiplier effect: a company sets up a factory, and suddenly, suppliers and distributors follow. As more manufacturing moves closer to the U.S., the need for warehouses grows. We believe this trend is a long-term tailwind for the industrial real estate sector.
“The companies that are ahead of the curve will be the ones best positioned to thrive in this new environment.”
But there’s more. The U.S. Inflation Reduction Act incentivized many companies to bring manufacturing stateside, especially in industries producing things like chips and solar panels. This trend may continue driving demand for warehouses and industrial space – not just for distribution but for manufacturing as well.
Of course, as with anything new, this shift is creating challenges on both sides of the supply and demand equation. In the U.S. at least, demand from a real estate perspective isn’t just about space. Power is increasingly critical. Companies need sites with reliable energy to support their operations, especially when it comes to data centers. The need for power and strategically located land is contributing to the rising demand of industrial properties. While there is a recognizable tailwind here, having local knowledge and operational know-how is vital.
Nearshoring is reshaping the warehouse real estate market. It’s not a short-term trend – this is a structural shift in how businesses manage their supply chains. As more companies look to diversify and de-risk their operations, nearshoring may continue to drive demand for industrial real estate in the U.S. and Mexico. The companies that are ahead of the curve will be the ones best positioned to thrive in this new environment.
The pandemic taught us many lessons, and for real estate investors, one of the most important is this: proximity matters. Whether it’s a medical company distributing vaccines or a manufacturer producing chips, businesses want to be closer to their customers. And that means they need more warehouse space, more industrial land, and more power. Nearshoring isn’t just a trend – it’s the future.
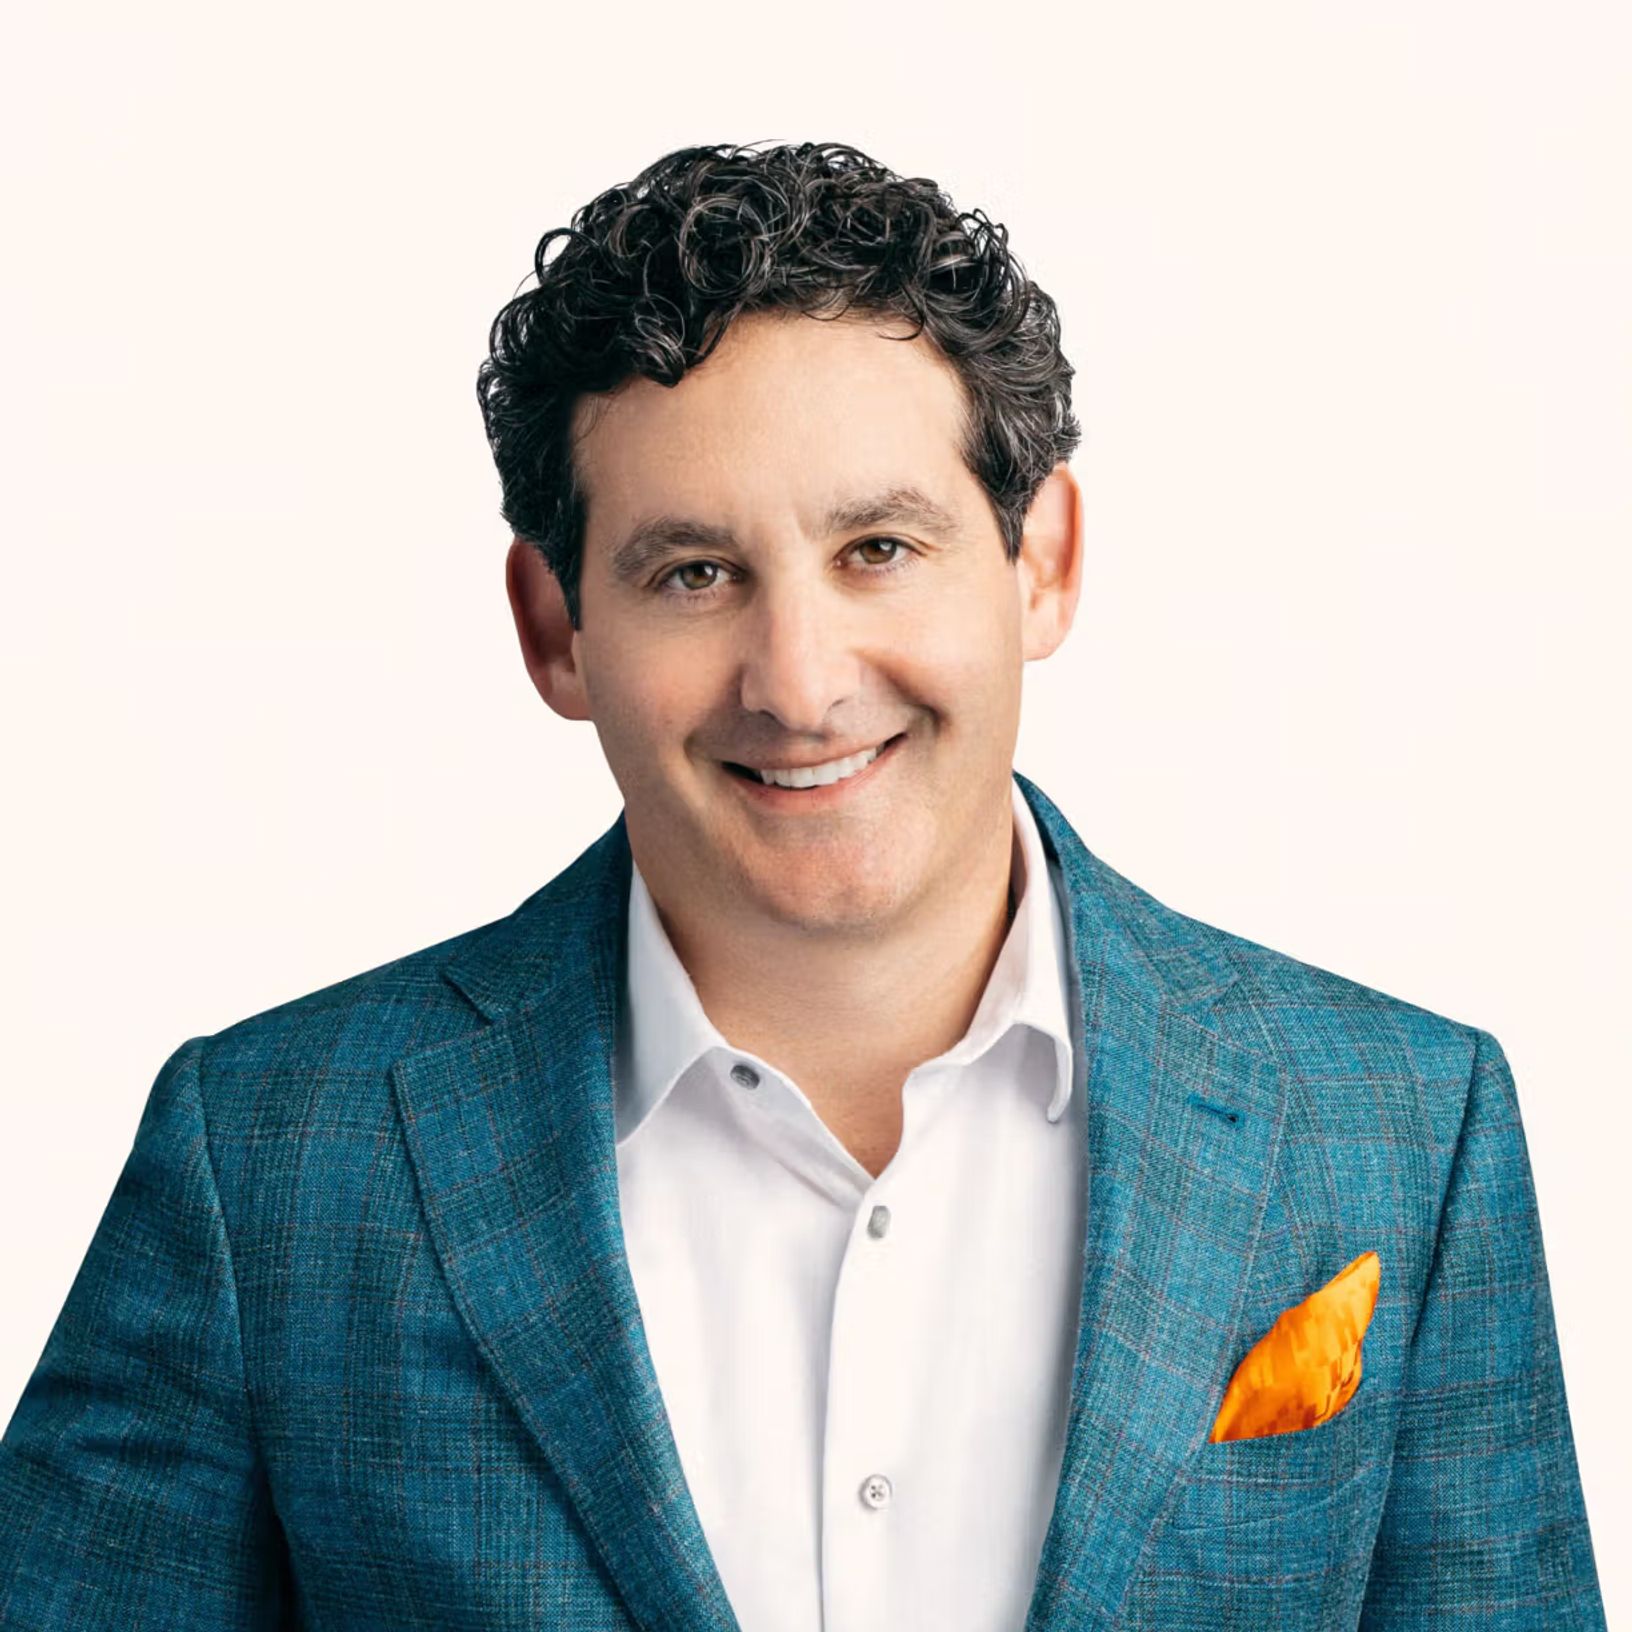
As global head of EQT Real Estate, Mr. Steinberg oversees EQT's real estate business, spanning industrial and residential strategies across the Americas, Europe, and Asia, and is a member of EQT's Executive Committee. Mr. Steinberg joined Exeter Property Group, now EQT Real Estate, in 2008, and brings decades of experience across real estate investment, development, management, and operations. He was previously the President of EQT Exeter North America and Co-Portfolio Manager of the U.S. Industrial Value Fund series. Prior to this role, he served as Investment Officer responsible for the Northeast region. Prior to joining EQT Real Estate, he worked for Liberty Property Trust from 2003 to 2008, where as a Director of Leasing & Development he was responsible for a 5.5 million square foot warehouse, flex and office portfolio and was part of the team that developed the Comcast Center, a 1.25 million sf skyscraper in Center City, Philadelphia. Prior to Liberty Property Trust, Mr. Steinberg worked at Arthur Andersen as a Senior Consultant in their Strategy, Finance and Economics practice. Mr. Steinberg earned a BA in Economics from the University of Pennsylvania and an MBA with a concentration in Finance from the Stern School of Business of New York University.

ThinQ by EQT: A publication where private markets meet open minds. Join the conversation – [email protected]


